For wholesale & eligible investors
Put your capital to work in secured New Zealand business loans with your name on the mortgage.
Co-fund short to medium term first and second mortgage business loans with HomeSec Business Finance, a private business lender lending since 2004, with its New Zealand office in Auckland. You choose each loan, you're named on the registered mortgage, and our own money sits alongside yours.
- Lending since 2004
- Our money in every loan
- Auckland office, NZ-wide lending

- Returns
- 12–18% p.a.
- Lending since
- 2004
- Maximum LVR
- 80% residential
- Typical loan term
- 1–12 months
- Per loan
- NZ$100k+ loans up to NZ$1m
A simpler, more transparent way to earn strong returns from New Zealand property.
Investment Opportunities lets wholesale investors lend directly into individual business loans arranged and co-funded by HomeSec Business Finance, a private business lender with its New Zealand office in Auckland. Each loan is secured by a registered first or second mortgage over New Zealand real estate, typically runs for 1 to 12 months, and pays returns of 12% to 18% p.a. You are named on the mortgage for your share.
It isn't a fund. There's no pooled money, no unit price, no redemption queue — just a real loan, a real property, and your name on the security. We fund most of our loans from our own balance sheet; on some, we invite a small group of investors to come in alongside us.
Why investors choose direct
Strong returns, and you stay in control.
Many pooled funds pay lower returns while asking you to hand over control of where your money goes. Co-funding flips that around.
Your name on the mortgage
You're named on the registered mortgage for your exact contribution — not a unit holder in someone else's pool.
You choose every loan
Each opportunity comes with a full due diligence pack. You decide yes or no, and how much. No obligation, ever.
Our money in every deal
HomeSec co-invests its own capital in every loan it offers to investors. We practise what we preach.
Paid straight to you
Principal and interest go directly to your own bank account — not to us, not into a fund.
No redemption freezes
Repaid at maturity. Want out early? We'll buy out your share and repay your principal on request.
No construction or development
Only straightforward business loans over existing property, with a maximum 80% LVR on residential.
Direct vs pooled
Lower returns and less control shouldn't come as a package deal.
When New Zealand finance companies and pooled mortgage funds froze between 2006 and 2012, many investors waited years for their money. Here's why a direct, registered position works differently.
| Typical pooled mortgage or credit fund | Co-funding with HomeSec | |
|---|---|---|
| What you own | Units in a fund | A share of a specific loan — named on the mortgage |
| Who chooses the loans | The manager | You, from a full due diligence pack |
| What you can see | Periodic, averaged reporting | The property, the borrower, the purpose and the exit |
| Getting your money out | Redemption requests — can be limited or frozen | Repaid at maturity, or bought out early by HomeSec |
| Manager's own money | Often none in the loans | In every loan, alongside yours |
| Construction & development | Often a large share of the book | None |
| Where repayments go | Into the fund | Straight to your bank account |
| Returns | Often single-digit | 12%–18% p.a. |
Read the full comparison: direct mortgage investment vs pooled funds →
“You are not left wondering how things work — and your return, or the security of your funds, isn't dependent on a whole heap of things going exactly right.”
Paul Stone, Joint CEO & FounderHow it works
Five steps. It really is that simple.
- 01
Register your interest
Tell us about yourself and confirm you're a wholesale or eligible investor. Our Funding Manager will call — or jump on a Zoom.
- 02
Review a loan pack
When a loan fits, we email its due diligence pack: the property, the borrower, the purpose, the exit, the LVR, the term and the rate.
- 03
Say yes — or pass
If you like it, tell us how much you'd like to contribute. If not, there's no obligation. You choose every loan.
- 04
Settle in your name
The loan agreement is prepared in your name, the borrower signs with their own lawyer, and the mortgage is registered on the title with you on it.
- 05
Get paid
Interest and principal are paid straight to your account. When the loan repays, take the next one — or don't.
Returns
Double-digit income, secured by New Zealand property.
Borrowers pay a premium for speed, flexibility and short terms — not because they're weak. Most are established businesses using the equity in their property. That premium is what you earn.
Backed by New Zealand property
Real property, honest numbers — and a buffer built for a downturn.
Values can fall. After the 2021 peak, New Zealand house prices fell about 16% nationally on REINZ's index, over roughly 18 months. We lend at today's values, to a maximum 80% LVR on residential property and lower on commercial, for typically 1 to 12 months — so a loan is only ever exposed to a slice of any downturn.
How the equity buffer protects your loan
Share of the property's value
- Your loan — no more than 80% of the property's value (lower on commercial)
- New Zealand's 2021–23 fall — about 16% nationally, over roughly 18 months
- Equity still protecting you — about 4% of value left, even after a fall of that size
 Auckland
 Wellington
 Christchurch
 Tauranga
 Hamilton
 Queenstown
An honest look at the New Zealand property market → Our lending rules →
Lessons from New Zealand
What the finance company collapses and Du Val taught investors.
Between 2006 and 2012, 51 New Zealand finance companies failed or froze payments. In 2024 the Du Val property group went into statutory management. What went wrong — and why a registered, loan-by-loan position is built differently.
The Du Val collapse: what happened, and what investors can learn
The Du Val collapse explained: three FMA warnings, statutory management of about 70 entities, what investors may recover, and the lessons for investors.
New Zealand finance company collapses: what went wrong, and what investors can learn
New Zealand finance company collapses, 2006 to 2012: 51 companies, about 200,000 investors, the patterns they shared and how to spot them in 2026.
Redemption freezes explained: how New Zealand mortgage funds came to be frozen
What is a redemption freeze? How a mortgage fund gets frozen, what happened to NZ funds and finance companies in 2008, and a structure with no pool to freeze.
The private lending experts
Founded in 2004. Lending our own money the entire time.
HomeSec Business Finance was founded in 2004 by Paul Stone and has lent its own money ever since. In New Zealand we lend from our Auckland office, and both joint CEOs are involved in every loan we fund — including the ones you co-fund.
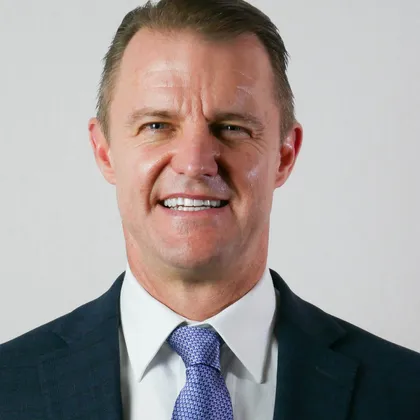
Paul Stone
Joint CEO & Founder
Founded HomeSec Business Finance in 2004 and wrote its first private business loan. Involved in every loan decision since.
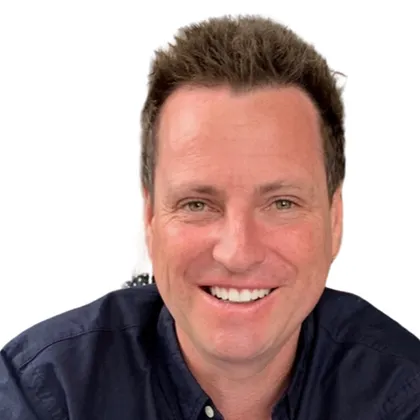
Jason Brockmuller
Joint CEO
Runs credit policy and the second-mortgage book. With HomeSec since 2008 and involved in every loan decision.
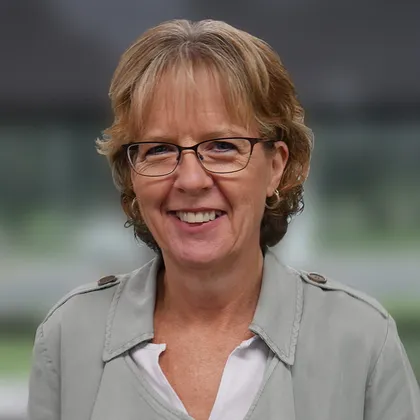
Catriona Anderson
Group General Manager
Signs off every credit decision the team writes. With HomeSec since 2005.
Who co-funds with us
Built for people who've already made the money.
Now it's about enjoying life and healthy returns — with full control. Our investors can be anywhere in New Zealand or overseas: review a pack on your phone, fund from your bank's app, and get on with your day.
Investor insights
All insights →- Private creditIs private credit safe in NZ? A 10-question test for investors
- Income investingTerm deposit alternatives in New Zealand, ranked by risk
- Pillar guidePrivate credit in New Zealand: a 2026 guide for wholesale investors
- Private creditContributory mortgage vs pooled mortgage fund in NZ, and where direct co-funding fits
- Seven-figure portfoliosWhere to invest $1 million in New Zealand, and the part secured income can play
- Family trustsCan a family trust invest in private mortgages in NZ? The Trusts Act, the paperwork and the tax
Questions
What investors ask us first.
Can't see your question? Call our Funding Manager on 09 888 6550, 7 days — or browse the full FAQ.
What is Investment Opportunities?
Investment Opportunities is the New Zealand investor programme of HomeSec Business Finance, a private business lender lending since 2004, with its New Zealand office in Auckland. Wholesale investors co-fund individual short to medium term business loans secured by registered first and second mortgages over New Zealand real estate. You choose each loan, you are named on the mortgage for your share, and HomeSec's own money sits in every loan alongside yours.
Is this a managed fund or a pooled mortgage fund?
No. You don't buy units in a pool. You lend into a specific loan you have reviewed, and you are named on the registered mortgage for your exact contribution, alongside HomeSec. There is no pooled money, no unit price, no redemption queue and no fund manager deciding where your capital goes.
What returns can I earn?
Returns are 12% to 18% p.a. on the loans you choose. The rate is set loan by loan and shown in each loan's pack before you commit. Established businesses pay a premium for speed, flexibility and short terms, not because they are weak borrowers, and that premium is what you earn.
How much can I put into each loan?
You decide, loan by loan. Co-funders choose how much to contribute to each loan, from NZ$100,000, on loans of up to NZ$1 million. There is never any obligation to take a loan, and HomeSec co-invests its own money alongside you in every loan it offers.
Can I get my money out before the loan matures?
Yes. If you want out early, ask us and HomeSec will buy out your share and repay your principal. You can also stop co-funding at any time: once your current loans are repaid, you simply don't take the next one. There is no redemption queue to join.
What security protects my investment?
A registered first or second mortgage over New Zealand residential or commercial real estate, with your name on it. The maximum LVR is 80% on residential property and lower on commercial, which leaves an equity buffer if a property ever has to be sold. Each loan's pack sets out the valuation and the LVR.
What happens if a borrower doesn't repay?
The mortgage is enforceable through the New Zealand courts and the mortgagee sale process under the Property Law Act 2007. It starts with a default notice giving the borrower not less than 20 working days to put things right. If the property is then sold, the lenders must take reasonable care to obtain the best price reasonably obtainable. HomeSec manages the process with specialist lawyers, with its own money in the same loan.
Does HomeSec invest its own money?
Yes, in every loan. HomeSec funds the majority of its loans from its own balance sheet and co-invests its own money in every loan it offers to investors. Its capital sits in the same loan, on the same mortgage, as yours, so it has every reason to lend carefully.
How do I qualify as an eligible investor?
You certify in writing that your previous experience acquiring or disposing of financial products lets you assess the merits of an offer, your own information needs and the adequacy of the information provided, and you state the grounds. A financial adviser, qualified statutory accountant or lawyer must confirm the certificate in writing. It is valid for two years.
Can my family trust or company co-fund loans?
Yes. The loan agreement and mortgage are prepared in the name of the trustees or the company, and repayments go to the entity's own bank account. The trust or company needs to qualify as a wholesale investor itself. Trustees should check the trust deed allows it and weigh their Trusts Act 2019 duty to invest prudently.
Register your interest
Get your money working for you.
Tell us a little about yourself. Our Funding Manager will be in touch during business hours — we'd love to have a chat, and jump on a Zoom if that suits you.
- No obligation to take any loan
- Your name on every mortgage you fund
- HomeSec's own money in every deal